NQ Weekly Profile Research: What 16 Years of Data Reveals
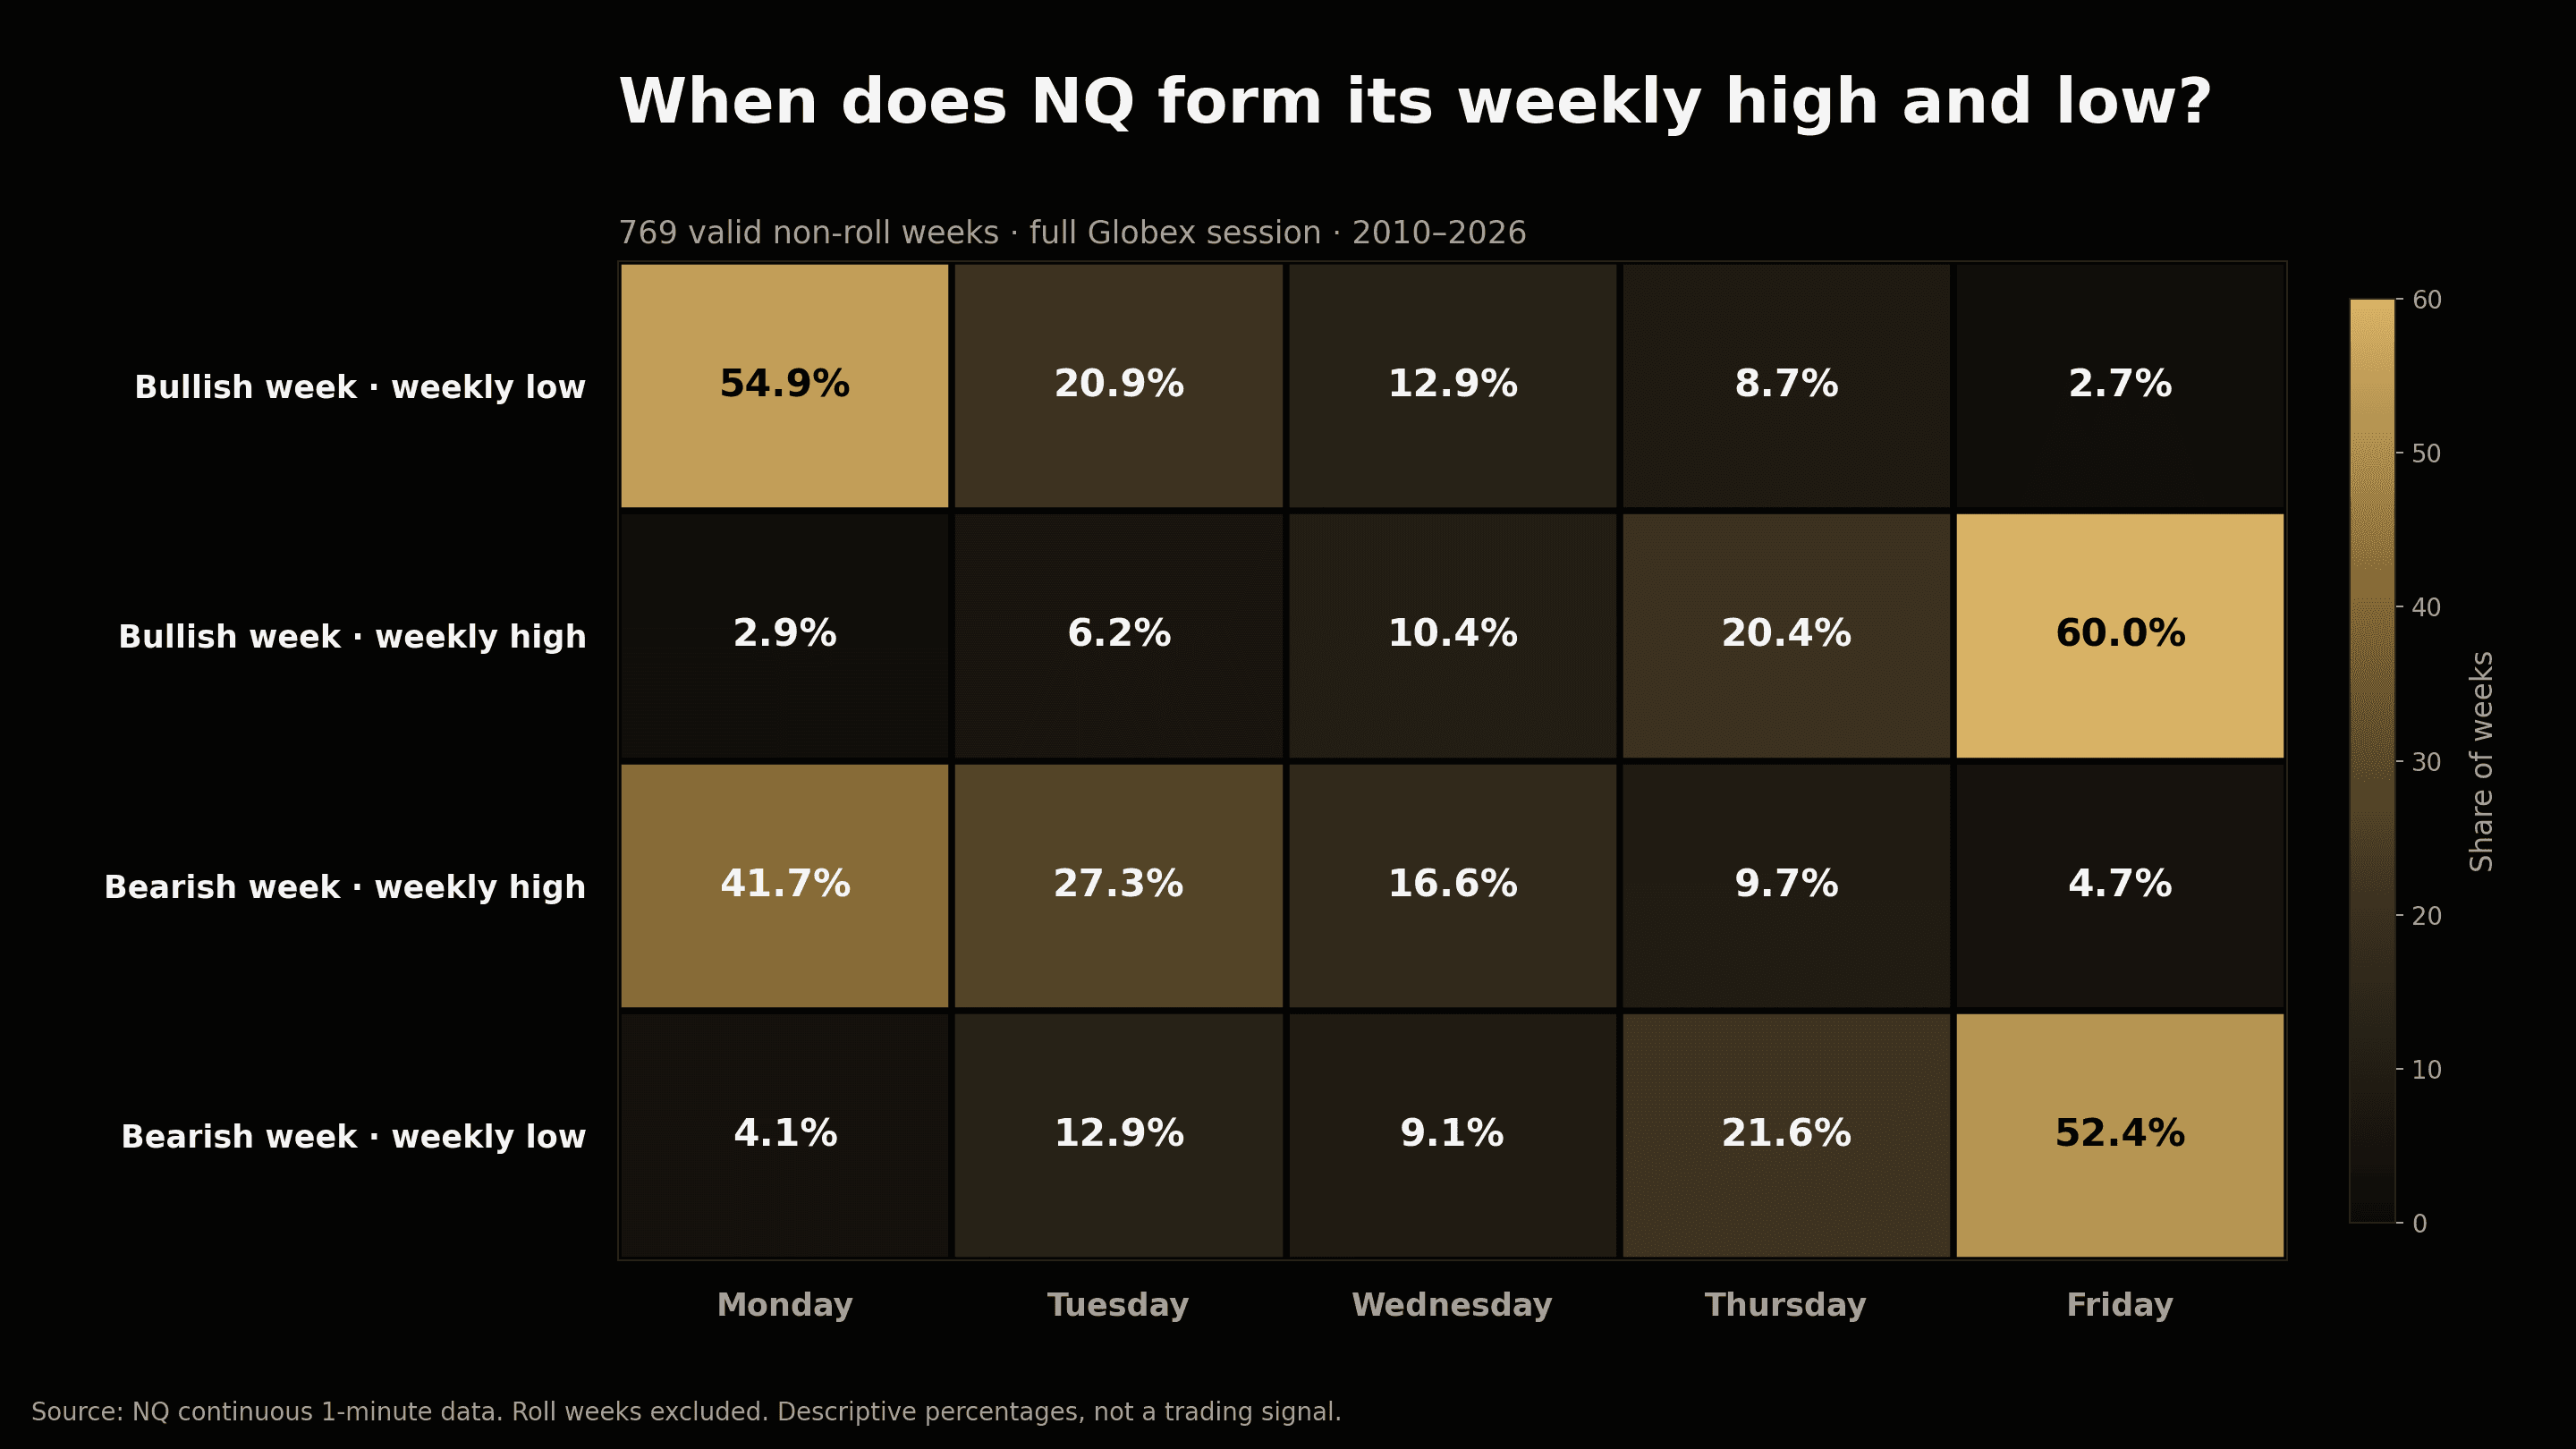
An empirical study of 769 non-roll NQ weeks maps when weekly extremes form, which price paths recur, and what Friday's close suggests about the following week.

Structured investigations and practical guides on market behavior, risk, execution, and the systems behind a durable trading operation.
An empirical study of 769 non-roll NQ weeks maps when weekly extremes form, which price paths recur, and what Friday's close suggests about the following week.

An NQ overnight-return study covering 2010–2025, with MNQ execution, risk and capital estimates. The selected rules failed internal validation; their partial 2026 results do not establish a stable net edge.
A three-window study of the first NQ liquidity pool reached in New York trading. A frozen directional model was accurate on selected forecasts, but did not outperform the nearest active pool on the same events.
An empirical study of NQ hourly origins, timing boundaries, session context and closing windows, separating recurring price structure from predictive value.
Research and education are useful only when their limits are visible. Every piece is classified by purpose and written to separate evidence from interpretation.
The claim, definitions, and decision being investigated are stated before the conclusion.
Assumptions, sample constraints, and failure conditions are part of the result.
Each article closes the loop between analysis and an action a trader can evaluate.
The historical data used in the published studies was obtained from Databento. The separate forward-testing workflow uses a bridge connected to TradingView.
Substantive corrections will be dated and explained in the affected article, with notices published on X or Substack.
For questions, feedback, or further information about these studies, contact research@thehermestrader.com.